
 English
 搜索
 联系我们


业务咨询/合作
010-68711086HR专线
010-62137913-8605 文章发布日期:
 阅读数:
On November 28, 2024, the closing ceremony of the 18th Shanghai Financial Services Fair and the 2nd Sci-tech
Innovation Finance Conference co-hosted by Shanghai Financial
Association and Lujiazui Financial City were held in Shanghai, during
which the Research Report on ESG Disclosure in Shanghai Financial Industry(2024) (Hereinafter referred to as “the Report”) was unveiled.
The
Report is the first research report about ESG disclosure in Shanghai
financial sector jointly released by Shanghai Financial Association and
GoldenBee Consulting.
The Report,
through abundant research, analysis and reviews, systematically
presents how much Shanghai financial enterprises know about ESG and the
status quo of ESG disclosure exploration and development. It summarizes
and reviews on the characteristics at this stage of ESG disclosure by
listed financial enterprises in Shanghai, and puts forward relevant
suggestions to provide references for financial institutions to act on
and develop ESG.
Ⅰ. Two major finding on ESG development of financial enterprises in Shanghai
(1) ESG philosophy widely recognized and stressed by Shanghai financial enterprises
Shanghai
financial enterprises have been fully aware of the importance of ESG
and has rolled out relevant work at different levels.
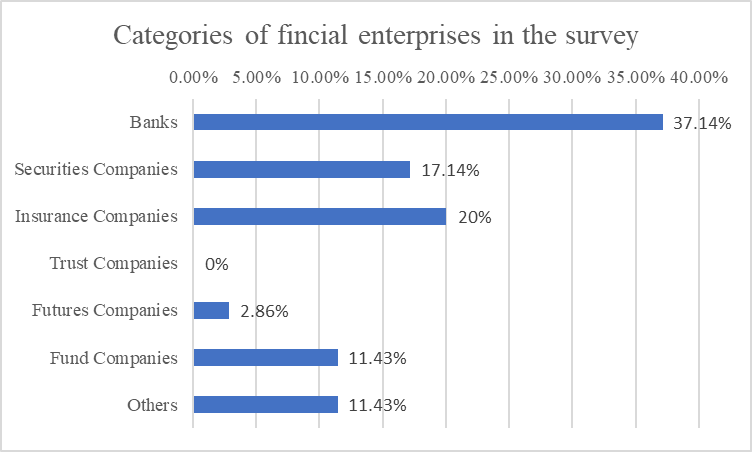
62.86%
of the enterprises state that their leaders have listed ESG among
their priorities and have been proactively urging different departments
to participate and endeavor in this regard. 5.71% of the enterprises
have everyone highly involved in and deeply implement ESG strategies. In
addition, 22.86% of them have ESG departments that are initially
exploring ESG-related work. A small number of the enterprise only have a
brief understanding of ESG but have not yet carried out actions
(5.71%). 2.86% of the enterprises have little knowledge about ESG and
have not paid attention to it.
(2) The quality of ESG reports of listed financial companies in Shanghai is above the average of Shanghai and China
Analyzed
from the six dimensions of integrity, reliability, readability,
comparability, creativity, innovation, substance, the reports released
by listed companies in Shanghai are outstanding in terms of innovation,
readability and integrity, with scores of 88.10%, 82.86% and 80.13%
respectively. The scores for reliability and comparability stood at
62.24% and 60.71% and the substance is scored 51.23%, relatively low.
However, the listed financial companies in Shanghai outperform the
average of Shanghai enterprises and Chinese enterprises in all of the
six dimensions, taking a lead in different aspects.
Ⅱ. The ESG development of financial enterprises in Shanghai shows three major characteristics at this stage
(1) The governance of the enterprises shows great momentum but strategic planning needs to be accelerated
Specifically,
the disclosure rates of the social responsibility management
structure and the participation, guidance or supervision of the board of
directors or top executive teams in the social responsibility
management are relatively high, accounting for 92.86% and
85.71% respectively. This indicates that these enterprises have
realized the importance of fulfilling ESG or social responsibility, have
strengthened the top-level design, and have set up a sound and
comprehensive ESG and social responsibility management structure and
that the senior executives have attached great importance to and have
got involved in relevant supervision and management.
The
disclosure rates of the integration of social responsibility into the
decision-making process of businesses and the visions and strategies of
social responsibility are relatively low, constituting 64.29% and 50%
respectively and showing much room for improvement.
(2) Environmental development takes initial form but lacks capital investment
In
terms of environmental management, Shanghai financial listed
enterprises have the highest disclosure rate in establishing an
environmental management system, which represents 71.43%, while the
disclosure rates of investment in environmental protection and
contribution to the industry's experience in improving environmental
management are relatively low, accounting for only 7.14% and 14.29%.
Enterprises
should establish special funds for energy conservation and
environmental protection, making great efforts in facilitating green and
environmental work. They should actively get engaged in forums and
activities on industrial green and low-carbon development, sharing and
promoting successful practices and cases so as to offer references for
different sectors in advancing green transformation.
(3) An active response to the calls of the government and a lack of response to social concerns
A
review of the disclosure rates of different
stakeholder-related indicators shows that listed financial companies in
Shanghai report the highest disclosure rate in responses to the
governments, which makes up 67.86%. The disclosure rates of responses to
media reaches 57.14%, to regulators, 53.57%, to peers, 52.38%, to
investors, 50%, to employees, 48.21%, to customers, 44.05%, all
surpassing 40% and are relatively high. By contrast, their disclosure
rates of responses to communities only stands at 33.93%, to suppliers,
28.57%, to financial institutions, 25%, and to civil societies, 22.62%,
which are relatively low, and call for more attention and improvement in
this regard.
Ⅲ. Four suggestions for financial enterprises in Shanghai
(1) Follow the new requirements and improve the quality of ESG disclosure
Financial
enterprises in Shanghai are the trailblazers, explorers and
practitioners of ESG philosophy. They should take initiatives to adapt
to and align with the new requirements for ESG disclosure, lay out plans
in advance and strengthen management, disclose ESG information
comprehensively, render the information disclosed more transparent and
reliable, and respond to the improving ESG ecosystem in a undisturbed
manner.
(2) Deeply fit into the ESG philosophy and join hands in building “the five key pillars”
Financial
enterprises in Shanghai should play a key role in expanding their
business to “promoting the five key pillars of sci-tech finance, green
finance, inclusive finance, elderly-care finance and digital
finance” based on their advantages. Meanwhile, they should plan for and
deploy the action plans in an overall manner under the framework of ESG
standards, taking into consideration the comprehensive benefits of
economy, society and environment.
(3) Align with the top-notch practices and address the weak links in ESG management
With
the purpose of achieving high-quality development, financial
enterprises in Shanghai should stay committed to adopting high standards
and fully borrow experience from the ESG management philosophy and best
practices of the first-class enterprises in China and the world. They
should locate their shortages, address their weak links,and carry
forward their strengths. Just as the adage goes, a stone taken from
another mountain may serve as a tool to polish the local jade. Financial
enterprises in Shanghai should be keen to learn from others and develop
ESG management modes with their own characteristics, which can be taken
as a starting point to improve ESG management. Enterprises should also
enhance their ability to resist risks, competitiveness, innovation, and
influence, offer valuable experience and guidance to the peers, and
maintain their leading position in developing ESG, so as to contribute
to a greener, fairer, and more transparent business environment.,
(4) Strengthen information transparency and build bridges of trust among stakeholders
Financial
enterprises in Shanghai should comprehensively identify their relevant
stakeholders, establish effective communication channels and mechanisms,
maintain positive and harmonious relationships, enlarge their circle of
friends, and identify the major needs of stakeholders. They should seek
opportunities for mutual benefits and use them as driving forces to
improve their ESG performance, coordinate resources and staff, and
develop strategies targeting specific ESG issues. ESG information and
data should be disclosed in a timely, accurate, and
comprehensive manner by conducting quantitative and qualitative analysis
to promote the transparency and authenticity of the information
disclosed and to systematically present the implementation and
significant outcomes of the actions taken by enterprises. Enterprises
should keep on tracking and improving information disclosure, achieve
convergence of interests in development, and foster close bonds with
stakeholders to gain their recognition and supports.